The latest federal budget from Canada introduces a modification to Registered Retirement Savings Plans (RRSPs), designed to streamline financial planning for numerous seniors annually.
Experts in taxation and personal finance indicate that while the proposed “RRSP for life” initiative could enhance convenience, it fails to tackle the challenges faced by seniors coping with escalating living expenses.
An RRSP is a Canadian savings vehicle that reduces current tax liability, allowing your savings and investments to accumulate tax-free until retirement. These accounts can accommodate a diverse range of financial assets, such as cash, stocks, guaranteed investment certificates (GICs), and exchange-traded funds (ETFs).
For the 2026 tax year, individuals may contribute up to 18% of their earned income from 2025, capped at a maximum of $33,810. If a workplace pension exists, the value of those contributions is subtracted from the 18% contribution limit.
Thursday’s federal budget includes a number of measures aimed at making life more affordable for Canadians. More low-income workers will get benefit payments to help them make ends meet. Those who make a minimum of $3,000 annually get a refundable tax credit under the Canada Workers Benefit, but that threshold is being lowered to $500 for all workers.
What are the proposed changes?
Presently, RRSPs must be converted to a Registered Retirement Income Fund (RRIF) or withdrawn when the account holder turns 71. In the new federal budget, the government suggests permitting Canadians to retain their RRSPs beyond that age.
At present, if an individual passes away after reaching 71 with a RRIF, the account can be transferred to a spouse without the need to close it or file tax documents. This is not currently the case for RRSPs.
The proposed budget from Ottawa would allow a surviving spouse or partner to take over as the successor holder of an RRSP, facilitating tax-free transfers to eligible survivors following the account holder’s death.
A public consultation regarding this initiative commenced on Thursday and will continue until January 8, 2027.
-
7 takeaways from the Carney government’s 2nd budget
-
Carney’s new budget aims to end homelessness in 10 years
Jamie Golombek, managing director of tax and estate planning at CIBC Private Wealth Management, noted that most individuals at age 71 typically opt to convert their RRSPs to RRIFs to avoid taxes imposed when cashing out.
“It’s a complex administrative task affecting at least hundreds of thousands each year,” he informed CBC News.
“What the government is proposing is, ‘Why not have an RRSP for life?’ Essentially, an RRSP that remains accessible until the account holder passes away.”
- Cross Country Checkup is asking: What sacrifices are you making to make ends meet? Is the federal government doing enough to lower your cost of living? Leave your comment here and we may read it or call you back for Sunday’s show
According to the suggested changes, the government would require RRSP holders to take a minimum percentage of their savings each year beginning at age 72. These percentages are determined based on average life expectancy to ensure that retirement savings are distributed and taxed gradually throughout the owner’s lifetime.
John Fragos, press secretary for Finance Minister François-Philippe Champagne, confirmed to CBC News that under the government’s proposal, RRSP account holders would be unable to contribute past the age of 71.
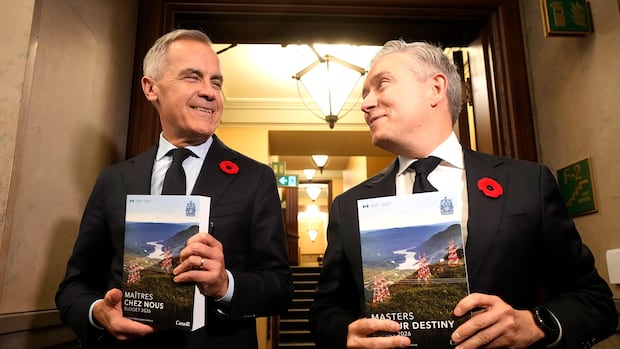
The Carney government’s second budget lays out over $150 billion in spending to attract investment, accelerate nation-building projects, boost housing and tackle the affordability crisis. The NDP says it favours the rich, while Conservatives call it a ‘credit card budget Canadians can’t afford.’
Why do the changes matter?
Aaron Hector, senior wealth advisor at Calgary’s Tier Wealth, believes that making the financial landscape easier for seniors is a wise action by the government. He commends the proposal to facilitate the transfer of RRSPs after a death.
“Avoiding the need for someone to navigate the paperwork to convert an RRSP into a RRIF seems to be a logical approach to me,” he stated. “Heaven forbid it goes unnoticed; it could lead to complications for individuals.”
Li Zhang, director of social impact at Chartered Professional Accountants of Canada, views the “RRSP for life” initiative as merely a change in terminology that overlooks more significant issues affecting seniors.
She estimates that only 33 to 37 percent of Canadians actually have access to a pension.
“The reality is, not many people possess substantial retirement savings,” she remarked. “If you’ve observed the queues at food banks, they are primarily occupied by the very young or the very elderly.”
She points out that another challenge for RRSP holders is that the required withdrawals can disrupt their income balance. “This can lead to increased taxation,” she noted.
Although the consultation phase for this proposal extends until January 8, Golombek anticipates that actual implementation of these changes may take considerably longer if Ottawa decides to proceed.
“I suspect it will be several years before we witness the complete integration of these changes, or at least the removal of the RRIF.”
